Published 8th September 2021- IFC Review
The Financial Action Task Force (FATF) was formed in 1989 with laudable objectives. It describes itself as the “global money laundering and terrorist financing watchdog”. It proceeds, therefore, on the serene assumption that to speak out against it and its methodology is to be against God, Motherhood and Apple Pie but in practice it is a hopelessly flawed organisation that has failed in its objectives and one that is increasingly driven by arbitrary prejudicial and purely political motivations of the EU. An objective analysis of the performance of the FATF over the past 30 years evidences systemic failure on an epic scale.
I recall being in the room in the Cayman Islands in the early 1990s when representatives of the FATF described the problem. We were told some US$2 trillion of criminal proceeds were being placed, layered, and integrated into the global financial system annually. It seemed a reasonable concern. And of course, at that time, the Cayman Islands had no financial transparency. Strict and novel measures were required to combat the problem and so the FATF forty recommendations of money laundering of 1990 were swiftly followed by the nine special recommendations and on terrorist financing in 2021. Thousands of trees have died in the past 30 years printing the subsequent FATF prognostications. But the net result after 30 years, according to the most recent EU Report of the European Credit Research Institute and Center for the European Policy Studies Report of January 2021[i] is that “a new approach is needed”. No doubt as John Cusack, an ex-chair of the Wolfsburg Group, estimates that the proceeds of crime now in circulation is closing in on US$5.8 trillion annually. All the FATF can show for its efforts and hundreds of billions of dollars of costs annually, according to the United Nations Office of Drugs and Crime, is that 0.2 per cent of that total is confiscated by law enforcement. In 2016, Europol estimated the confiscation rate in Europe to be as high as a paltry 1.1 per cent.[ii]
Any organisation in the private sector displaying results of that sort would have long since ceased to exist. But as leading economist, Dan Mitchell, writes in “The Pointless Burden of Anti Money Laundering Laws,[iii] the response of the FATF will be to double down on an epically flawed system. He is wrong about that. The multiple will be many times more than double because like the OECD, with which the FATF shares office facilities in Paris, and a good many other EU based organisations, the FATF is incapable of any meaningful self-analysis or any reconsideration of a failed philosophy.
We can now conclude without doubt that the fundamental failure of the FATF approach was to seek to shift the obligation to interdict crime from law enforcement to the private sector through the mechanisms of know your client (KYC), source of funds due diligence, and suspicious activity reporting. More recently, moving from a certified schedule of FATF approved jurisdictions on which financial institutions and others could place reliance to a country risk assessment made by the individual made matters risibly worse. The subjective concept of risk assessment is an unsound basis for criminal sanction. We also can say with certainty that suspicious activity reporting has become nothing other than an indemnity seeking exercise. According to figures from Europol, of the 1.1 million SARS reported across the EU in 2019, only 10 per cent were further investigated by public authorities and within the EU, only 1.1 per cent of criminal profits were confiscated as a result.[iv]
The founding principles of the FATF talk loftily of “proportionate” responses. But the cost of the foregoing mechanisms and the hopelessly flawed risk-based approach is entirely disproportionate. A Nexis Lexis report in April 2020, “The True Cost of Financial Crime Compliance Global Report”, estimated the annual cost of financial crime compliance at around US$181 billion per annum.[v] You can do the math on the costs over 30 years. But this is a gross underestimate given the methodology applied which focused on large, medium, and small institutions and then multiplied the average by the number of firms in the given market. The initial proposals of the FATF have been uselessly extended without thought to the cost of compliance. The initial representations in that room in the Cayman Islands in 1990 were that KYC and source of funds due diligence should be done once at the point of placement of the monies into the financial system by the relevant financial institution (and who is better placed to undertake meaningful analysis on source of funds?) and every other service provider thereafter could rely on that due diligence. The elegance of this concept has been entirely bastardised by the FATF in that now, every single service provider in the chain, whether it is in actual receipt of the monies, must undertake like analysis of the same dollar. That is particularly offensive to financial institutions in the Cayman Islands through which monies in a typical open ended or closed ended fund structure will typically pass only electronically and particularly, given the certain knowledge that the KYC and source of funds checks must in any event be undertaken at the point of introduction of the monies to an investor’s account by the financial institution with which the investor is most closely connected and by the ultimate recipient prime broker, administrator or fund manager located in a major money centre. The truth is that the FATF know that money laundering occurs but have no idea of where or how to look for it.
Basel Index
This hopelessly flawed thinking is mirrored by a non-transparent group of clowns responsible for creating something called the “Basel Index” which, like the FATF, suggests that smaller jurisdictions like the Cayman Islands are at high risk to money laundering when the contrary is the case. Anyone who might understand how money laundering operates in practice will know that the money launderer needs a major financial market in which to operate effectively and that it is the major financial centres which are therefore the locations where monies must be placed and integrated. Credit to the US International Narcotics Control Strategy Report which, contrary to the FATF analysis, gets this point right. The evidence of actual money laundering, to which the FATF are blind, confirms the correct narrative. If we analyse the known cases of money laundering, in 2010 it was found that drug cartels in Mexico laundered US$390 billion through Wachovia Bank in Miami. In 2012, Standard Chartered laundered US$265 billion for the Iranian Government in breach of Anti Money Laundering sanctions. In 2010, Danske Bank, Denmark’s largest bank with the assistance of Deutsche Bank, laundered US$228 billion through its Estonian branch. In 2014, BNP Paribas was fined US$9 billion by the US authorities for transactions with countries blacklisted by the United States. Semion Mogilevich, reputably of the Russian Mafia, laundered US$10 billion through the Bank of New York at exactly the time when the then Attorney General of New York, Robert Morgenthau, in conjunction with Senator Carl Levin, were accusing the Cayman Islands of being a hot bed of money laundering. The problem with their suggestions is that there is and was simply no evidence of comparable or indeed statistically relevant money laundering in the Cayman Islands at all. Unlike the position in 1990, the Cayman Islands are now completely financially transparent. The money flows into the Cayman Islands are all electronic and can be readily tracked. Those flows emanate from the very 205 countries and the financial institutions in them (in fact in the main 10 per cent of that number) that are members of the FATF.
So not only is there no such evidence of money laundering in the Cayman Islands but since every law enforcement authority and tax authority of note has an unrestricted right to establish the verified beneficial ownership of every legal entity registered in the Cayman Islands and to investigate any account in the Cayman Islands, we can conclude that either all onshore law enforcement and tax authorities are completely incompetent or the FATF do not have the slightest idea of what they are talking about in grey listing the Cayman Islands and thereby requiring increased monitoring of its financial transactions.
Further, the FATF, in including the Cayman Islands on their recent grey list, has persuaded the dunderheads in the UK Treasury to include the Cayman Islands in their list of high-risk countries in the Money Laundering and Terrorist Financing (Amendment) (High Risk Countries) Regulations 2021 and all without evidence of a predicate money laundering offence. Mr. Marcus Pleyer, the President of the FATF, cannot be stupid but he is evidently frustrated and that is leading to poor decisions. He flails at the problem complaining “the vast majority of countries are failing to tackle money laundering”. But he is the architect of his own confusion in allowing the system to be based on meaningless attempts to evaluate risk rather than to focus on hard evidence of source of funds. And he fails to give credit where it is due; the law and regulation in the Cayman Islands, and indeed the Overseas Territories and Crown Dependencies in general, on verified beneficial ownership is world leading and leaves the unverified shambles at London Companies House in its wake. If that is right, and it cannot on any technical analysis be controverted, then the reaction of the FATF in grey listing the Cayman Islands is nothing short of perverse and politically motivated. It certainly has nothing to do with money laundering. Mr. Pleyer should know better than to seek his inspiration from the notable French essayist, Baudelaire who said, “the greatest trick the devil ever pulled was convincing the world he didn’t exist”. The greatest trick of the FATF has pulled is to seek to convince the world that the absence of convictions for money laundering in the Cayman Islands or, even more preposterously, the absence of fines imposed by the Cayman Islands regulator for failure to adhere to anti money laundering procedures, must be evidence of the fact that money laundering exists in the Cayman Islands and that it is simply not being detected. Since we and the US Federal Reserve know, and the FATF should know, there are no cash deposits of any significance in the Cayman Islands and transparency is established, so the reverse is the truth. However frustrated Mr. Pleyer may be, it must be wrong in principle for the FATF to create a structure under penalty of law which relies on smear tactics and requires the accused to prove a counterfactual.
Corrupt Logic
What is particularly pernicious about the FATF’s corrupt logic is that it insidiously erodes one of the fundamental tenets of a robust and well-functioning common law legal system by extending extraterritorially the worst aspects of the European Union regulatory and legal approach. It ought to be a fundamental of the United States, English, Cayman Islands, and other common law systems that the burden of proof cannot be reversed. But regrettably, we find that the Cayman Islands regulators, for fear of arbitrary and prejudicial FATF black or grey listing, have wittingly or unwittingly acquiesced in the FATF approach and seek to apply fines with no indication whatsoever of a predicate money laundering offence.
The problems with the FATF can be attributed to its increasingly close political connection with the EU. Tax avoidance was included as a money laundering offence under the Fourth AML Directive since which the black and grey lists of the EU List of Non- Cooperative Tax Havens and the EU High Risk Third Country List (anti money laundering), which are ostensibly separate, have increasingly developed the common objective of extending EU tax policy extraterritorially and with which the FATF has become politically intertwined.
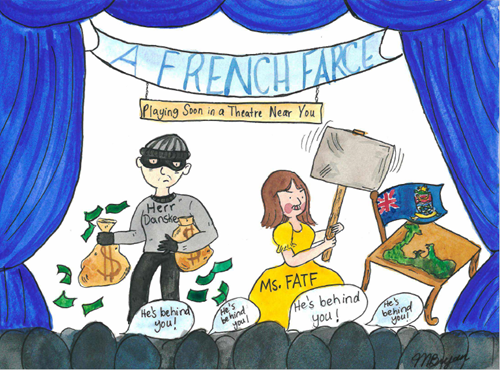
The FATF system, in its arbitrary application of the EU’s favoured blacklist tactic, has become dangerously prejudicial and not fit for purpose. The organisation and the entire architecture of the anti-money laundering bureaucracy needs to be deconstructed. A cursory review of the FATF budget and the hundreds of billions of dollars spent annually on failed compliance would be better spent on funding law enforcement to prevent the criminal activity in the first place. In doing so, a more effective approach would be to focus law enforcement on the acquisition of assets and properties in the onshore jurisdictions. Unexplained Wealth Orders are a sensible approach that should target the money launderer at the right end of the chain. The notion that jurisdictions like the Cayman Islands, which are institutional and not retail and whose financial structures conduit funds from and into the major international financial centres, are involved in predicate money laundering offences, is nonsense and entirely politically motivated.
The illustration, by Michelle Bryan, was commissioned by the author.
Footnotes:
[i] Anti-Money Laundering in the EU, Time to Get Serious, January 2021
[ii] https://www.europol.europa.eu/newsroom/news/does-crime-still-pay
[iii] The Pointless Burden of Anti-Money Laundering Laws (freedomandprosperity.org)
[iv] https://www.ceps.eu/wp-content/uploads/2021/01/TFR_Anti-Money-Laundering-in-the-EU.pdf
[v] https://risk.lexisnexis.com/about-us/press-room/press-release/20200407-fcc-global-study
The Financial Action Task Force (FATF) was formed in 1989 with laudable objectives. It describes itself as the “global money laundering and terrorist financing watchdog”. It proceeds, therefore, on the serene assumption that to speak out against it and its methodology is to be against God, Motherhood and Apple Pie but in practice it is a hopelessly flawed organisation that has failed in its objectives and one that is increasingly driven by arbitrary prejudicial and purely political motivations of the EU. An objective analysis of the performance of the FATF over the past 30 years evidences systemic failure on an epic scale.
I recall being in the room in the Cayman Islands in the early 1990s when representatives of the FATF described the problem. We were told some US$2 trillion of criminal proceeds were being placed, layered, and integrated into the global financial system annually. It seemed a reasonable concern. And of course, at that time, the Cayman Islands had no financial transparency. Strict and novel measures were required to combat the problem and so the FATF forty recommendations of money laundering of 1990 were swiftly followed by the nine special recommendations and on terrorist financing in 2021. Thousands of trees have died in the past 30 years printing the subsequent FATF prognostications. But the net result after 30 years, according to the most recent EU Report of the European Credit Research Institute and Center for the European Policy Studies Report of January 2021[i] is that “a new approach is needed”. No doubt as John Cusack, an ex-chair of the Wolfsburg Group, estimates that the proceeds of crime now in circulation is closing in on US$5.8 trillion annually. All the FATF can show for its efforts and hundreds of billions of dollars of costs annually, according to the United Nations Office of Drugs and Crime, is that 0.2 per cent of that total is confiscated by law enforcement. In 2016, Europol estimated the confiscation rate in Europe to be as high as a paltry 1.1 per cent.[ii]
Any organisation in the private sector displaying results of that sort would have long since ceased to exist. But as leading economist, Dan Mitchell, writes in “The Pointless Burden of Anti Money Laundering Laws,[iii] the response of the FATF will be to double down on an epically flawed system. He is wrong about that. The multiple will be many times more than double because like the OECD, with which the FATF shares office facilities in Paris, and a good many other EU based organisations, the FATF is incapable of any meaningful self-analysis or any reconsideration of a failed philosophy.
We can now conclude without doubt that the fundamental failure of the FATF approach was to seek to shift the obligation to interdict crime from law enforcement to the private sector through the mechanisms of know your client (KYC), source of funds due diligence, and suspicious activity reporting. More recently, moving from a certified schedule of FATF approved jurisdictions on which financial institutions and others could place reliance to a country risk assessment made by the individual made matters risibly worse. The subjective concept of risk assessment is an unsound basis for criminal sanction. We also can say with certainty that suspicious activity reporting has become nothing other than an indemnity seeking exercise. According to figures from Europol, of the 1.1 million SARS reported across the EU in 2019, only 10 per cent were further investigated by public authorities and within the EU, only 1.1 per cent of criminal profits were confiscated as a result.[iv]
The founding principles of the FATF talk loftily of “proportionate” responses. But the cost of the foregoing mechanisms and the hopelessly flawed risk-based approach is entirely disproportionate. A Nexis Lexis report in April 2020, “The True Cost of Financial Crime Compliance Global Report”, estimated the annual cost of financial crime compliance at around US$181 billion per annum.[v] You can do the math on the costs over 30 years. But this is a gross underestimate given the methodology applied which focused on large, medium, and small institutions and then multiplied the average by the number of firms in the given market. The initial proposals of the FATF have been uselessly extended without thought to the cost of compliance. The initial representations in that room in the Cayman Islands in 1990 were that KYC and source of funds due diligence should be done once at the point of placement of the monies into the financial system by the relevant financial institution (and who is better placed to undertake meaningful analysis on source of funds?) and every other service provider thereafter could rely on that due diligence. The elegance of this concept has been entirely bastardised by the FATF in that now, every single service provider in the chain, whether it is in actual receipt of the monies, must undertake like analysis of the same dollar. That is particularly offensive to financial institutions in the Cayman Islands through which monies in a typical open ended or closed ended fund structure will typically pass only electronically and particularly, given the certain knowledge that the KYC and source of funds checks must in any event be undertaken at the point of introduction of the monies to an investor’s account by the financial institution with which the investor is most closely connected and by the ultimate recipient prime broker, administrator or fund manager located in a major money centre. The truth is that the FATF know that money laundering occurs but have no idea of where or how to look for it.
Basel Index
This hopelessly flawed thinking is mirrored by a non-transparent group of clowns responsible for creating something called the “Basel Index” which, like the FATF, suggests that smaller jurisdictions like the Cayman Islands are at high risk to money laundering when the contrary is the case. Anyone who might understand how money laundering operates in practice will know that the money launderer needs a major financial market in which to operate effectively and that it is the major financial centres which are therefore the locations where monies must be placed and integrated. Credit to the US International Narcotics Control Strategy Report which, contrary to the FATF analysis, gets this point right. The evidence of actual money laundering, to which the FATF are blind, confirms the correct narrative. If we analyse the known cases of money laundering, in 2010 it was found that drug cartels in Mexico laundered US$390 billion through Wachovia Bank in Miami. In 2012, Standard Chartered laundered US$265 billion for the Iranian Government in breach of Anti Money Laundering sanctions. In 2010, Danske Bank, Denmark’s largest bank with the assistance of Deutsche Bank, laundered US$228 billion through its Estonian branch. In 2014, BNP Paribas was fined US$9 billion by the US authorities for transactions with countries blacklisted by the United States. Semion Mogilevich, reputably of the Russian Mafia, laundered US$10 billion through the Bank of New York at exactly the time when the then Attorney General of New York, Robert Morgenthau, in conjunction with Senator Carl Levin, were accusing the Cayman Islands of being a hot bed of money laundering. The problem with their suggestions is that there is and was simply no evidence of comparable or indeed statistically relevant money laundering in the Cayman Islands at all. Unlike the position in 1990, the Cayman Islands are now completely financially transparent. The money flows into the Cayman Islands are all electronic and can be readily tracked. Those flows emanate from the very 205 countries and the financial institutions in them (in fact in the main 10 per cent of that number) that are members of the FATF.
So not only is there no such evidence of money laundering in the Cayman Islands but since every law enforcement authority and tax authority of note has an unrestricted right to establish the verified beneficial ownership of every legal entity registered in the Cayman Islands and to investigate any account in the Cayman Islands, we can conclude that either all onshore law enforcement and tax authorities are completely incompetent or the FATF do not have the slightest idea of what they are talking about in grey listing the Cayman Islands and thereby requiring increased monitoring of its financial transactions.
Further, the FATF, in including the Cayman Islands on their recent grey list, has persuaded the dunderheads in the UK Treasury to include the Cayman Islands in their list of high-risk countries in the Money Laundering and Terrorist Financing (Amendment) (High Risk Countries) Regulations 2021 and all without evidence of a predicate money laundering offence. Mr. Marcus Pleyer, the President of the FATF, cannot be stupid but he is evidently frustrated and that is leading to poor decisions. He flails at the problem complaining “the vast majority of countries are failing to tackle money laundering”. But he is the architect of his own confusion in allowing the system to be based on meaningless attempts to evaluate risk rather than to focus on hard evidence of source of funds. And he fails to give credit where it is due; the law and regulation in the Cayman Islands, and indeed the Overseas Territories and Crown Dependencies in general, on verified beneficial ownership is world leading and leaves the unverified shambles at London Companies House in its wake. If that is right, and it cannot on any technical analysis be controverted, then the reaction of the FATF in grey listing the Cayman Islands is nothing short of perverse and politically motivated. It certainly has nothing to do with money laundering. Mr. Pleyer should know better than to seek his inspiration from the notable French essayist, Baudelaire who said, “the greatest trick the devil ever pulled was convincing the world he didn’t exist”. The greatest trick of the FATF has pulled is to seek to convince the world that the absence of convictions for money laundering in the Cayman Islands or, even more preposterously, the absence of fines imposed by the Cayman Islands regulator for failure to adhere to anti money laundering procedures, must be evidence of the fact that money laundering exists in the Cayman Islands and that it is simply not being detected. Since we and the US Federal Reserve know, and the FATF should know, there are no cash deposits of any significance in the Cayman Islands and transparency is established, so the reverse is the truth. However frustrated Mr. Pleyer may be, it must be wrong in principle for the FATF to create a structure under penalty of law which relies on smear tactics and requires the accused to prove a counterfactual.
Corrupt Logic
What is particularly pernicious about the FATF’s corrupt logic is that it insidiously erodes one of the fundamental tenets of a robust and well-functioning common law legal system by extending extraterritorially the worst aspects of the European Union regulatory and legal approach. It ought to be a fundamental of the United States, English, Cayman Islands, and other common law systems that the burden of proof cannot be reversed. But regrettably, we find that the Cayman Islands regulators, for fear of arbitrary and prejudicial FATF black or grey listing, have wittingly or unwittingly acquiesced in the FATF approach and seek to apply fines with no indication whatsoever of a predicate money laundering offence.
The problems with the FATF can be attributed to its increasingly close political connection with the EU. Tax avoidance was included as a money laundering offence under the Fourth AML Directive since which the black and grey lists of the EU List of Non- Cooperative Tax Havens and the EU High Risk Third Country List (anti money laundering), which are ostensibly separate, have increasingly developed the common objective of extending EU tax policy extraterritorially and with which the FATF has become politically intertwined.
The FATF system, in its arbitrary application of the EU’s favoured blacklist tactic, has become dangerously prejudicial and not fit for purpose. The organisation and the entire architecture of the anti-money laundering bureaucracy needs to be deconstructed. A cursory review of the FATF budget and the hundreds of billions of dollars spent annually on failed compliance would be better spent on funding law enforcement to prevent the criminal activity in the first place. In doing so, a more effective approach would be to focus law enforcement on the acquisition of assets and properties in the onshore jurisdictions. Unexplained Wealth Orders are a sensible approach that should target the money launderer at the right end of the chain. The notion that jurisdictions like the Cayman Islands, which are institutional and not retail and whose financial structures conduit funds from and into the major international financial centres, are involved in predicate money laundering offences, is nonsense and entirely politically motivated.
The illustration, by Michelle Bryan, was commissioned by the author.
Footnotes:
[i] Anti-Money Laundering in the EU, Time to Get Serious, January 2021
[ii] https://www.europol.europa.eu/newsroom/news/does-crime-still-pay
[iii] The Pointless Burden of Anti-Money Laundering Laws (freedomandprosperity.org)
[iv] https://www.ceps.eu/wp-content/uploads/2021/01/TFR_Anti-Money-Laundering-in-the-EU.pdf
[v] https://risk.lexisnexis.com/about-us/press-room/press-release/20200407-fcc-global-study